A claim can be digitally submitted in minutes yet remain operationally stalled for days when policy, payment, repair, fraud, and customer data sit across disconnected systems. The top insurance claims automation tools address this gap, but enterprise value does not come from automating a single workflow. It comes from creating a governed claims operating model where data, decisions, controls, and human expertise work together.
For insurers and takaful operators, tool selection should therefore begin with the business architecture. The question is not simply which platform can process a claim fastest. It is which combination of platforms can improve cycle time, decision consistency, leakage control, customer communication, regulatory traceability, and the quality of data available for underwriting and risk decisions.
What enterprise claims automation should achieve
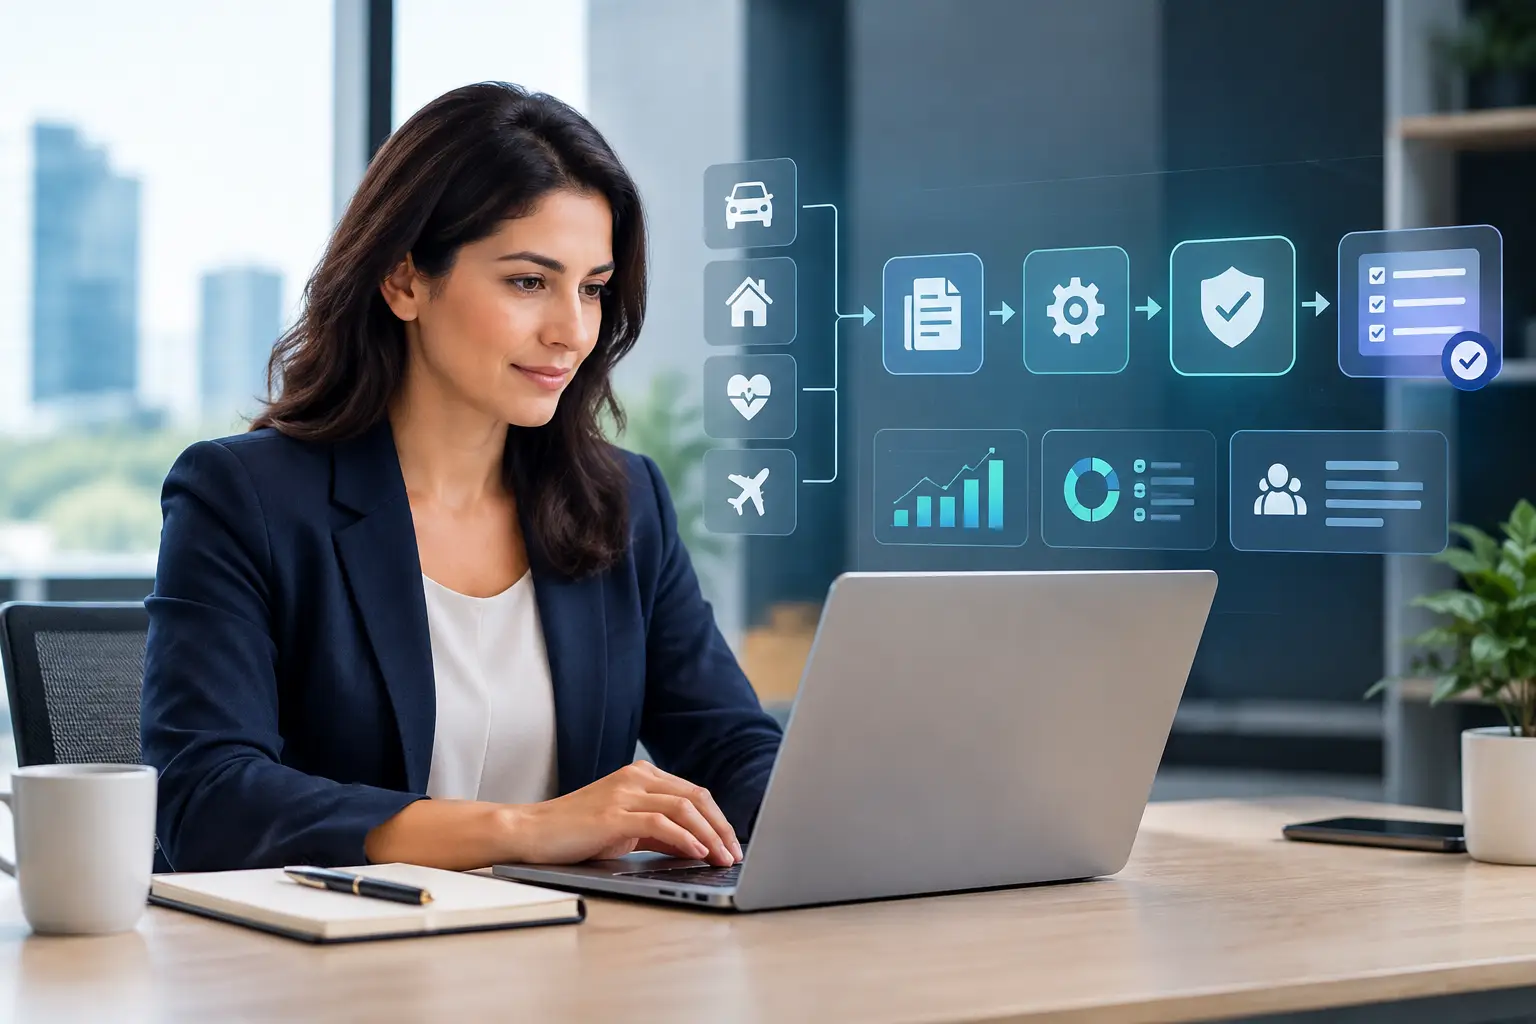
Claims automation spans the full lifecycle: first notice of loss, coverage verification, document intake, fraud screening, triage, assessment, reserve management, settlement, recovery, and closure. Mature programs do not attempt to remove people from every decision. They route straightforward, low-risk work to automated paths and provide adjusters with timely, explainable information for complex or sensitive cases.
That distinction matters. A high-volume motor claim with complete evidence may qualify for straight-through processing. A liability claim with uncertain coverage, potential fraud signals, or significant customer impact should move through a controlled human review path. The platform must support both without creating separate, ungoverned processes.
The tools below are not a universal ranking. Their suitability depends on an insurer’s core-policy environment, distribution model, lines of business, data maturity, cloud and sovereignty requirements, and modernization roadmap.
7 top insurance claims automation tools to evaluate
1. Guidewire ClaimCenter
Guidewire ClaimCenter is a core claims management platform used by property and casualty insurers to manage claim intake, assignment, financials, vendor coordination, and resolution workflows. It is generally most relevant for insurers pursuing broad core-platform modernization rather than a point solution for one claims bottleneck.
Its value lies in establishing a common operational system of record across claims teams and lines of business. However, implementation success depends heavily on process design, data migration discipline, integration architecture, and the degree of customization introduced. Insurers should protect upgradeability by distinguishing genuinely differentiating workflows from legacy practices that should be retired.
2. Duck Creek Claims
Duck Creek Claims provides claims management capabilities within a broader insurance platform environment. It is suitable for carriers seeking configurable workflows, policy and claims alignment, and support for product or process change without rebuilding the operating model from the ground up.
The evaluation should focus on how well the platform fits the organization’s target architecture. This includes integration with policy administration, digital channels, payment services, document management, repair networks, and enterprise analytics. Configurability can accelerate business change, but only when governance prevents uncontrolled variations in claim rules and process definitions.
3. Sapiens ClaimsPro
Sapiens ClaimsPro is designed to support claims operations across multiple insurance segments, with capabilities for workflow management, claims handling, and operational visibility. For organizations managing diverse products or maintaining complex legacy estates, its breadth can be relevant.
The critical question is whether the implementation can establish a consistent data model and standardized claims controls across business units. Without that foundation, a new platform can reproduce fragmentation under a modern interface. Leaders should define common claim states, coding standards, authority limits, and data ownership before configuring workflows.
4. Snapsheet
Snapsheet focuses on digital claims processes, including appraisal and claims management capabilities, particularly in property and casualty contexts. It can be valuable where insurers need to improve digital intake, estimating, virtual assessments, or coordination with external service providers.
This type of specialist platform is often most effective when deployed against a clearly bounded operational problem, such as reducing appraisal turnaround time or improving the customer experience for straightforward claims. It should not be assessed in isolation. Integration with the core claims system, evidence repositories, payment controls, and customer communication channels determines whether it improves the end-to-end process or adds another operational handoff.
5. CCC Intelligent Solutions
CCC Intelligent Solutions is widely associated with automotive claims and collision repair ecosystems. Its capabilities can be relevant to insurers seeking better connectivity among carriers, repair facilities, vehicle data, estimates, and claims teams.
For motor insurers, ecosystem connectivity can materially influence claim duration and repair outcomes. Yet external data and partner workflow integration introduce governance responsibilities. Insurers need clear standards for data quality, consent, audit trails, vendor performance measurement, and exception handling. Automation should make repair decisions more transparent, not less accountable.
6. FRISS
FRISS is focused on trust, fraud detection, and risk assessment within insurance processes. It can support insurers in prioritizing claims that require additional scrutiny while allowing lower-risk cases to progress with less manual intervention.
Fraud automation should be treated as decision support, not an opaque rejection engine. Risk scores need appropriate thresholds, monitoring for false positives, documented escalation paths, and human review for consequential decisions. The strongest deployments combine fraud signals with claims history, policy data, network relationships, payment patterns, and investigator feedback in a governed analytical environment.
7. Pega Platform
Pega is a low-code platform that can be used for case management, decisioning, customer service, and workflow automation, including insurance claims use cases. It may suit enterprises that need to orchestrate work across multiple existing systems rather than replace every core platform at once.
Its flexibility can be valuable for modernizing claims journeys incrementally. For example, an insurer may automate intake, correspondence, exception routing, and service requests while retaining its existing policy and claims systems of record. The trade-off is architectural discipline: enterprise teams must avoid creating a new layer of unmanaged business logic outside core governance and data controls.
Select tools through architecture, not demonstrations
Vendor demonstrations often show a clean claim journey with complete documents, predictable rules, and no integration failures. Real claims operations are defined by exceptions: missing evidence, policy ambiguities, third-party dependencies, manual overrides, duplicate records, and changing regulations.
A stronger evaluation uses representative scenarios drawn from the insurer’s own portfolio. Test a simple claim, a suspected fraud case, a complex injury or liability case, a claim requiring multiple documents, and a claim that crosses channels or business units. Evaluate not only task automation, but also the ability to explain decisions, recover from failures, retain audit evidence, and route work to the right authority.
Enterprise architecture teams should also assess whether each tool can participate in a governed data ecosystem. Claims platforms generate high-value operational data, but it is often underused because definitions differ across policy, finance, actuarial, customer, and risk functions. A trusted data foundation can reconcile these domains, preserve lineage, and make claims information available for decision intelligence without exposing sensitive data beyond authorized use.
Data governance is a claims capability
Claims automation creates more data, more events, and more automated decisions. That raises the importance of governance rather than reducing it. Senior leaders should establish accountability for claim data definitions, data-quality monitoring, retention, access controls, model inputs, and decision auditability.
This is particularly important when document intelligence, machine learning, or generative capabilities are introduced. A tool may extract information from repair estimates, medical records, police reports, or customer correspondence, but the organization remains accountable for the accuracy, privacy, and use of that information. Human validation thresholds and exception workflows need to be explicit.
ORTECH’s approach to AI-ready data is relevant here: automation becomes more sustainable when operational platforms feed a governed data architecture, rather than becoming isolated sources of untraceable decisions. This supports claims operations today while preparing the enterprise for broader analytics modernization.
Build the roadmap around measurable outcomes
A practical roadmap usually starts with one claims journey where the operational problem and baseline measures are clear. Targets may include first-contact resolution, claim cycle time, touchless processing rate, adjuster capacity, documentation completeness, fraud referral quality, payment accuracy, or customer complaint reduction.
The first release should integrate the minimum data and controls required to produce a reliable result. Once the organization has validated workflow performance and data quality, it can extend automation to adjacent claim types, additional channels, or more advanced decisioning. This phased approach is often safer than attempting a wholesale replacement while legacy data issues remain unresolved.
The most effective claims automation program is not defined by how many activities are automated. It is defined by whether every claim receives an appropriate, timely, explainable decision – supported by trusted data and accountable operational controls.